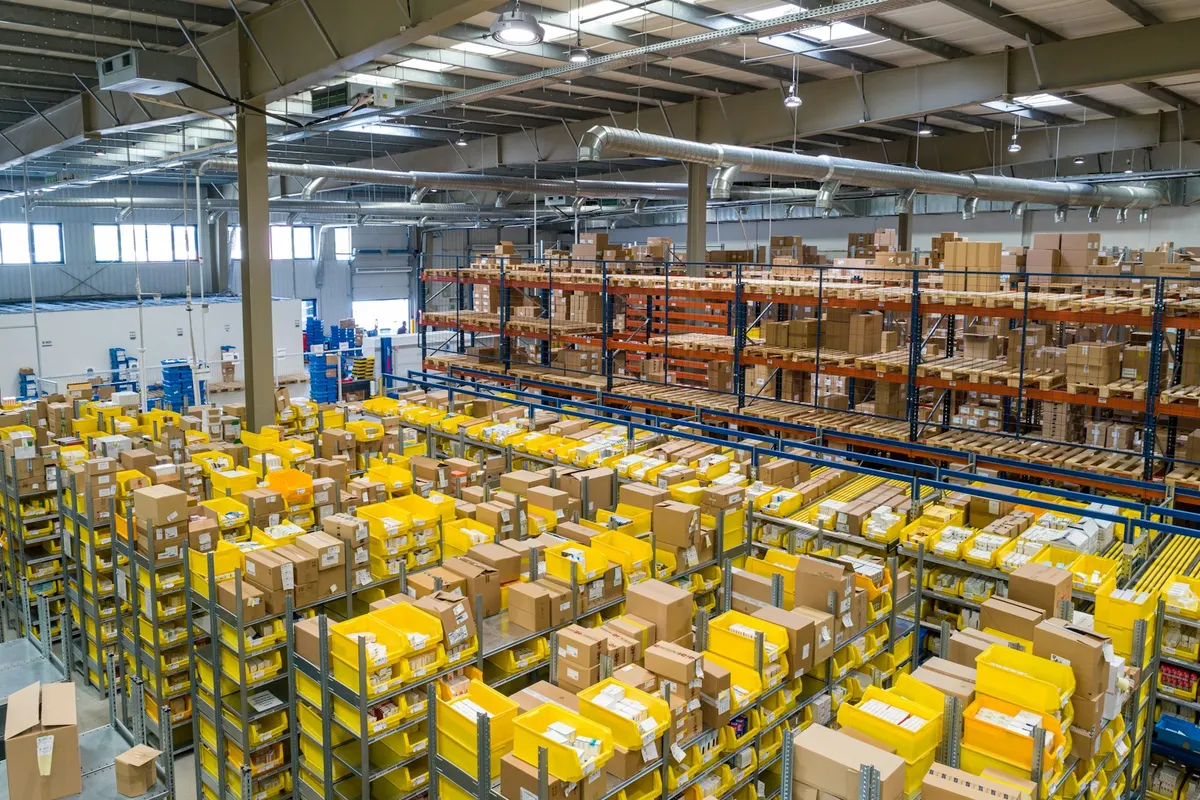
To find out your stock value, count the units of each item you hold on a fixed date, multiply each count by the cost of one unit, and add the results together. The total is the value of your stock at cost. It is the figure that appears as a current asset in your accounts, and it is the input that most stock calculations, such as turnover, depend on.
The method is simple, but the details decide whether the number is useful. You need an accurate count, a unit cost you can trace to an invoice, and a rule for what to do when the cost of the same item changes during the year. This guide walks through each step, shows a worked example and lists the errors that most often make a stock value wrong. A free inventory turnover calculator can take your opening and closing stock values once you have them.
Why stock value matters
Stock is often the largest asset a product business holds, after cash and receivables. Its value at cost affects the profit you report for the period, because the cost of goods sold is calculated from opening stock, purchases and closing stock. If the closing stock is overstated, profit looks higher than it is. If it is understated, profit looks lower, and the next period carries the error.
Stock value also tells you how much cash is tied up on the shelf. A business that holds a large stock of slow items may have plenty of inventory and little cash to pay suppliers. Knowing the figure helps you decide what to buy next and what to discount or clear.
What you need before you start
Gather four things before the count begins. Missing one of them is the most common reason a stock valuation has to be redone.
- A list of every item you hold, with a stock code or name that matches your purchase invoices.
- The cost of one unit for each item, taken from the purchase invoice, including delivery and import charges that you pay to bring the goods to the place where you hold them.
- A cut-off date, such as the last day of the month, and a rule to stop receiving and dispatching stock while you count.
- A record of stock that is damaged, expired or unsaleable, so you can value it separately or write it off.
Step-by-step: find out your stock value
- Choose the cut-off date and stop movements for the count, or record every movement that happens during the count.
- Count each item at every location where you keep it: the warehouse, the shop floor, a van, and stock sent to a fulfilment partner that you still own.
- Write down the unit cost for each item from the latest purchase invoice that applies. If the cost changed during the period, follow the valuation method you use every time.
- Multiply the count by the unit cost for each line. A count of 240 units at a cost of 3.50 gives 840.
- Add all the lines to get the total stock value at cost.
- Check the total against the previous period and against your purchases and sales. A large unexplained change usually means a miscount, a wrong cost or a missed movement.
Worked example with three items
Assume a small business holds three items on 31 October. The unit costs come from the most recent invoice for each item, and the amounts are in one currency. The example is a method illustration, not a benchmark.
| Item | Units counted | Cost per unit | Stock value at cost |
|---|---|---|---|
| Cable set, 2 m | 240 | 3.50 | 840.00 |
| Wall bracket, steel | 95 | 12.00 | 1,140.00 |
| Starter kit, boxed | 18 | 64.00 | 1,152.00 |
| Total | 3,132.00 |
The total of 3,132 is the closing stock value at cost for this example. If the opening stock the month before was 2,900, the change of 232 shows the net effect of purchases and sales, and you can check it against the invoices you received and the orders you dispatched.
Choosing a cost method
When the price of an item changes during the period, you have to decide which cost goes on the units still in stock. Accounting frameworks allow several methods, and the rules differ between countries. Two common approaches are first in, first out, where the oldest cost is used first, and weighted average cost, where the total cost of the stock is divided by the number of units. Whichever method you choose, use it consistently and note it in your records.
| Method | How it works | When owners use it |
|---|---|---|
| First in, first out (FIFO) | Remaining units carry the cost of the most recent purchases, because the oldest units are assumed to have sold first | Goods with a shelf life or prices that change often, when you want the balance sheet to reflect recent costs |
| Weighted average cost | Total cost of stock divided by the number of units, recalculated after each purchase | Many identical items bought at different prices, where tracking each batch is not practical |
| Specific identification | Each unit or batch carries its own cost, recorded when it is bought | High-value, individually numbered items such as machines or serialised equipment |
Ask your accountant which method your local rules allow and which one fits your records. Do not change the method during the year without a reason you can explain, because a change alters the profit you report.
Common mistakes that distort stock value
- Counting only the main warehouse. Stock in the shop, in a vehicle or at a partner site is still part of the value if you own it.
- Using the selling price. Stock is valued at cost, so you should not add your expected margin or use the price on the shelf label.
- Counting goods you have not received. Stock on order from a supplier belongs in the period when you receive and own it, which depends on the delivery terms.
- Forgetting damaged or expired items. Stock that cannot be sold should be valued at what you can recover, or written off, not counted at full cost.
- Mixing units. A cost per box multiplied by a count of single items gives a value that is wrong by the size of the box.
Keeping the figure up to date
A stock value calculated once a year tells you very little. Most businesses calculate it at each month end, because that is when the accounts are closed and when a count is easiest to organise. Between counts, a movement log that records each receipt and each dispatch lets you estimate the current value without stopping the warehouse. Our guide on how to do a stock count step by step explains how to plan a count that does not disrupt sales.
Once the value is accurate, you can compare it with sales over the same period. The result shows how fast stock moves, which is the basis of turnover. For systems that keep stock movements, costs and sales in one place, look at what Dika Ops covers for inventory and finance. If you would like to see how stock valuation would work in your own operation, you can talk to us and we will show you the process with your data.
Frequently asked questions
Is stock value the same as the selling price of my stock?
No. Stock is valued at cost, which is what you paid to acquire and prepare the goods for sale. The selling price includes your margin and is not used in the accounts for closing stock. If the net selling price falls below cost, the stock must be written down.
How often should I count stock to find the value?
Many businesses count at the end of each month or quarter and count the full stock once a year. The right frequency depends on how much stock you hold and how quickly it changes. Whatever you choose, use the same cut-off date rule every time.
What if the cost of an item changes during the year?
Apply the cost method you have chosen, such as FIFO or weighted average, and record the change. Do not replace the cost of stock already on the shelf with a new price without applying the method. Your accountant can confirm the approach that your local rules require.
Do I include stock held by a fulfilment partner?
Yes, if you still own the goods. Ask the partner for a statement of the units held on your behalf and value them at your cost. Goods sold to a customer but not yet delivered are usually not part of your stock on the date of sale, so check the terms of sale.
Can a spreadsheet give me an accurate stock value?
A spreadsheet can give an accurate value if the item list, unit costs and counts are correct and the formulas are checked. The main risk is a copied or out-of-date cost. Keep a note of where each unit cost came from, and reconcile the total with your accounts at each period end.
Next step
Choose one product group, count it on a single date, and value it using the invoice cost for each item. Compare the total with your previous month-end figure and explain the difference. Then use the inventory turnover calculator with your opening and closing values to see how quickly the stock moves. You can also read our guide to inventory management methods to decide how to organise the items you hold. Items that have not moved for months need separate treatment, which our guide on how to manage dead stock covers. Our free tools include a reorder point calculator for the step after valuation, and if your stock data sits in several places, our data platforms and business intelligence work covers how to bring it together. You can find more about our work on the Dika Design home page.


